The seller plans to take a wall-mounted screen. The buyer assumes it comes with the house. A fixture question turns that everyday disagreement into a classification problem: is the item personal property, or has it become part of the real estate? Work from attachment, adaptation, intention, the parties' relationship and their agreement. One dramatic detail rarely settles every case.
Begin with attachment and agreement
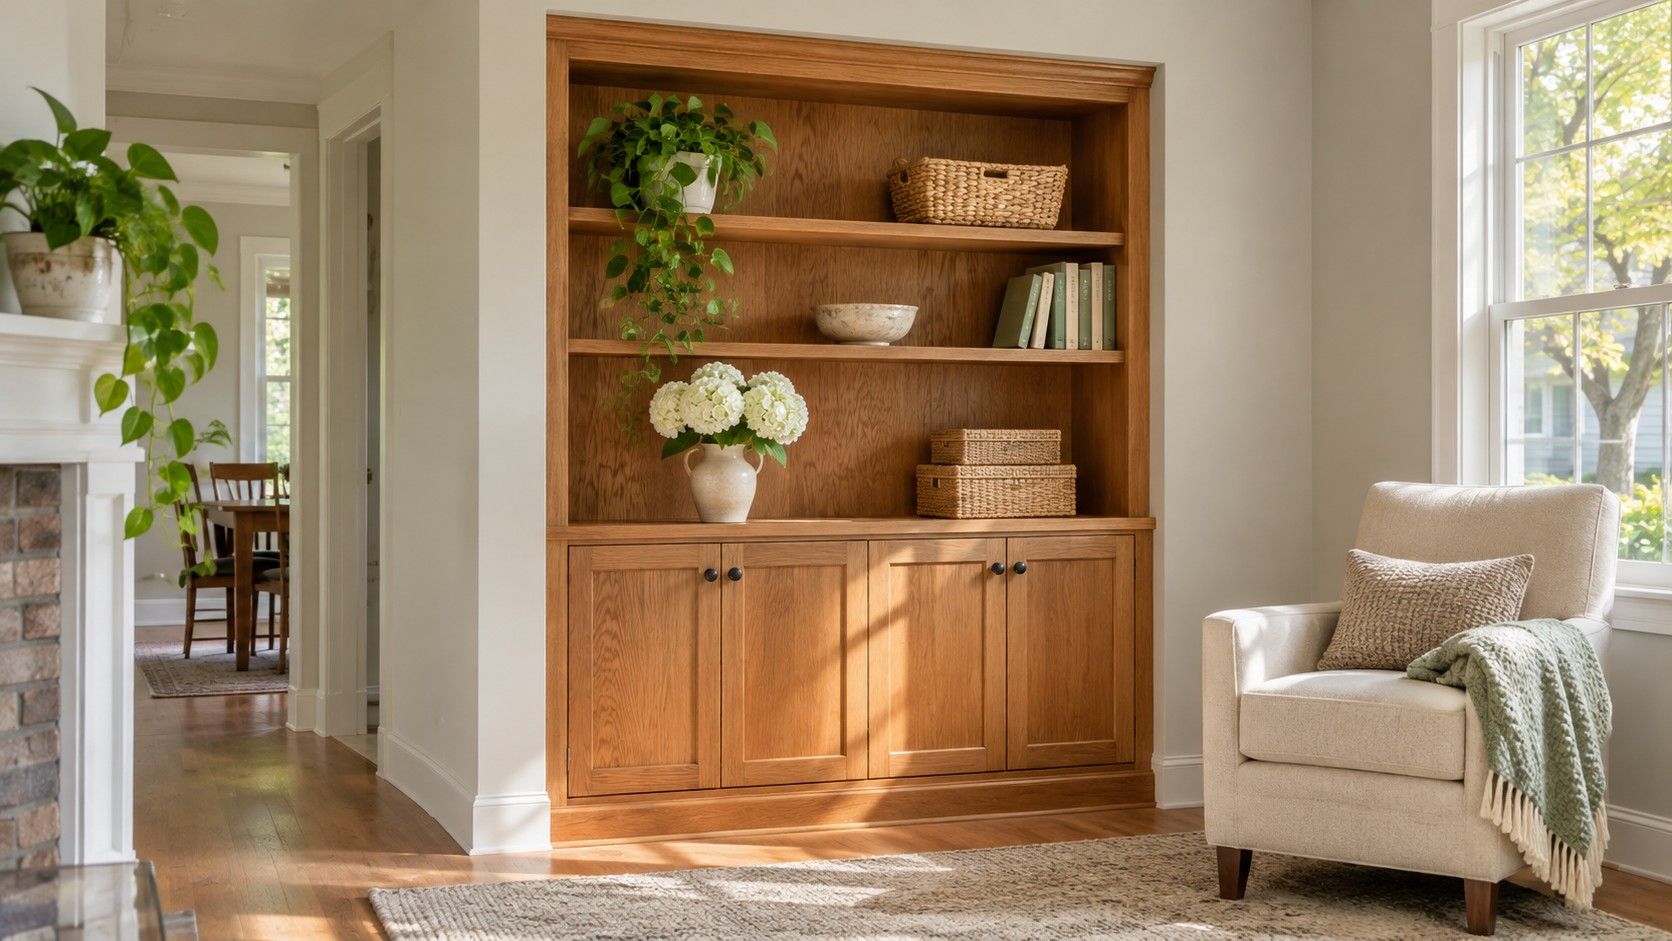
Physical attachment is a useful starting point, but “it can be unscrewed” is not a complete legal test. Many things regarded as fixtures can be removed with ordinary tools. A built-in cabinet and a freestanding bookcase may both hold books, yet their connection to the building and intended permanence differ. Ask what the installation shows about the item's relationship to the property.
Adaptation asks whether the item was fitted to the premises. Custom storm windows sized for particular openings illustrate a different connection from a standard lamp that can move from one room to another. Intention is usually inferred from circumstances rather than an owner's unspoken plan. The stem may describe the method of installation, the purpose of the improvement and the conduct of the parties. Those facts are more useful than guessing what the seller secretly wanted.
An express agreement can avoid an argument between the contracting parties. If a purchase contract clearly excludes a specified chandelier and the seller handles the exclusion as required, the question may be testing the agreement rather than a default classification rule. Do not ignore a written inclusion or exclusion because you memorized a fixture acronym. The purpose of the factors is to help analyze uncertainty, not to override every fact supplied in the bargain.
Why a tenant installation changes the analysis
A trade fixture is generally an item installed by a tenant for the tenant's business. That concept does not mean every object used in trade is automatically removable in all circumstances. The lease terms, removal timing, damage and applicable law matter. A dentist's specialized equipment installed in leased office space invites a trade-fixture analysis; a landlord's central heating system does not become the tenant's trade fixture merely because it supports the business.
Examine the relationship before comparing the hardware. Landlord and tenant interests may be treated differently from seller and buyer interests. A question that identifies who installed an item and why is giving you a reason to consider that distinction. If the tenant installed shelving for a shop and the lease addresses removal, read that clause. If the landlord installed permanent building improvements, do not import a tenant's business-removal privilege without supporting facts.
Timing can be decisive. A question may specify removal during the lease term or an abandoned installation after possession ends. Avoid memorizing one universal deadline for all states. General study questions should state the rule or remain at the conceptual level. If the stem names a jurisdiction, its lease law and the current exam material control. The safest explanation identifies the condition that permits removal rather than declaring that trade fixtures can always be taken.
Do not mistake use for ownership
An appliance can be important to a household and still be personal property. An ordinary freestanding refrigerator does not necessarily become a fixture because the family uses it daily. Conversely, an item with little independent value may be part of the real estate when it is integrated into a system. Usefulness and price are not substitutes for analyzing the installation and agreement.
Think about the difference between a light bulb and the installed lighting fixture, or between a loose garden ornament and landscaping rooted in the soil. A question may combine familiar objects with a fact that changes their status. Avoid answering from the object name alone. “Refrigerator,” “antenna” or “shelving” can describe several different installations, so the facts about attachment and intended permanence do real work.
Also distinguish fixture disputes from financing interests. An item might be subject to a separate security interest, a lease or a service agreement. A basic classification question may not require you to solve those additional rights unless they appear in the stem. Do not invent a lender, a rental agreement or a recorded filing. Answer the issue asked, while recognizing that a real transaction would require document review before promising that an item conveys free of all claims.
Work an original fixture question
Original practice situation: A seller installs a custom cabinet permanently into an alcove. It matches the room's dimensions, is fastened to the walls and is treated as part of the room. The purchase contract contains no exclusion. Which fact most strongly supports treating it as a fixture? A: The seller bought it with a credit card. B: It cost less than the sofa. C: Its attachment and adaptation indicate intended permanence. D: The buyer likes its color.
C is the best supported answer. The method of payment does not decide whether the cabinet became part of the real property. Price relative to another item is also irrelevant to the classification. The buyer's preference cannot create the seller's intended installation. Notice that C uses multiple relevant facts; it does not claim that any screw in a wall automatically settles every fixture dispute.
Now change the facts. A retailer leasing the space installs removable display units for the store, and the lease expressly permits removal before the term ends if damage is repaired. The tenant's business purpose and the lease support a different analysis. A learner who answers both situations with “attached means permanent” is missing the relationship and agreement. For practice, write a three-line note for each object: who installed it, how it serves the premises, and what the contract says. That is much more transferable than remembering a list of objects that supposedly always stay. When an actual purchase is being negotiated, specific written inclusions and exclusions are usually clearer than relying on assumptions about classification.